Brent crude jumped to nearly $110 a barrel this week — its highest since May — then gave part of it back, easing to around $107 by Tuesday. For anyone old enough to remember the fuel queues of the 1970s, the number alone is enough to raise the pulse. Economists are looking somewhere else.
Their argument is uncomfortable for headline-watchers: the price of a barrel is a spotlight, not a thermometer. What actually decides whether an oil spike damages the US economy is how much of a household's income it swallows, how long it stays elevated, and whether it leaks into the price of everything else people buy.
Brent's Climb to $110 Was Fast — and Speed Is the First Warning Sign
The move this week was sharp. Brent climbed as high as nearly $110 a barrel on Monday, up about 4% on the day, before cooling to roughly $107 on Tuesday — the highest level since May.
Speed matters more than the level. A slow drift higher gives freight companies, airlines and manufacturers time to adjust contracts and routes. A sudden jump forces decisions in days: fuel surcharges, renegotiated supply deals, postponed investment.
The immediate worry flagged by analysts was the familiar one. Higher crude feeds into transport, freight and factory costs, which can nudge inflation up and complicate the path of borrowing costs. That chain is why a barrel price makes front pages at all.
In 1980, Americans Spent About 6% of Income on Petrol. That Comparison Explains Everything
JPMorgan's analysis offers the cleanest way to understand why the $100 threshold has lost some of its power. Back in 1980, Americans spent roughly 6% of their income on gasoline, the bank's research found — a function of heavier driving, thirstier cars and relatively high prices.
That single statistic reframes the whole debate. A barrel price only becomes an economic shock when it collides with a household budget that cannot absorb it. Change the budget, and the same price means something different.
The Real Threat Isn't the Price of Oil — It's What the Price Does Next
Economists typically split the question into three parts. The first is pass-through: whether higher crude shows up in core inflation, the measure that strips out volatile food and energy, or stays quarantined in fuel and fades. The second is duration — a two-week spike is a news cycle, while six months at triple digits is a tax on growth. The third is expectations: if households and businesses start assuming permanently higher inflation, wage demands follow, and central banks are forced to respond harder.
None of those three has clearly tipped yet. That is the substance behind the claim that $100 isn't the real threat — not complacency, but the absence of evidence that the shock is spreading.
Who Feels $100 Oil First — and Who Barely Notices
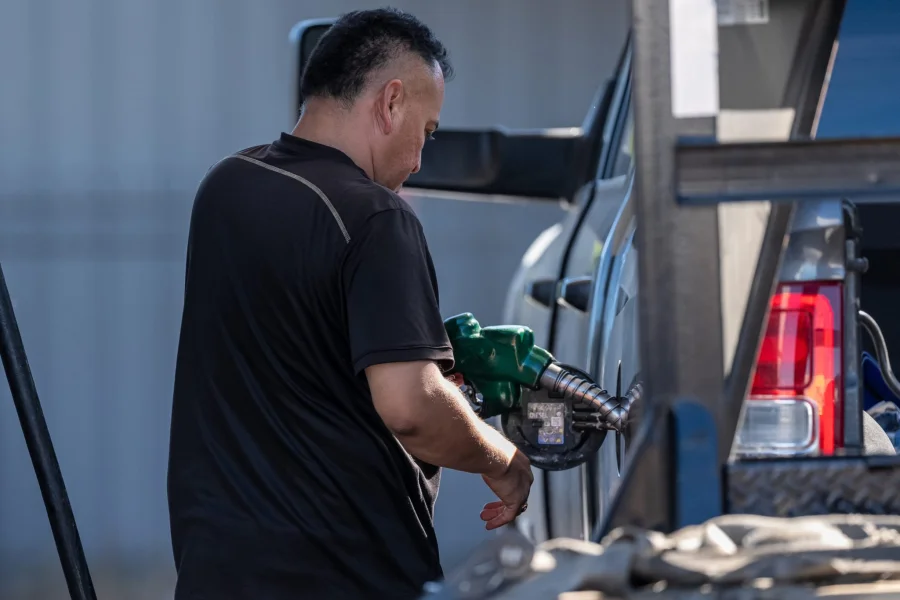
For a long-haul trucker, a cab driver, a farmer running diesel equipment, or a family in a district where a car is the only route to a hospital, an oil spike arrives almost immediately, at the pump. Airlines, logistics firms and small manufacturers feel it through fuel and freight bills within weeks.
For a remote worker in a city with reliable public transport, or a household where energy is a small slice of monthly outgoings, the same price is background noise. The aggregate "US economy" figure hides that gap — and the gap is precisely why $100 doesn't bite the way it once did.
What the 1980 Comparison Gets Right — and Where It Breaks Down
As a measure of scale, the 1980s analogy is useful. As a forecast, it is weak. Today's US economy produces each dollar of output with far less energy than it did four decades ago, and its energy mix has shifted substantially — trends energy economists have documented for years. That weakens the mechanical link between the barrel price and GDP.
What hasn't changed: oil is priced globally, it still moves inflation expectations, and it still has an outsized grip on how people feel about the economy. Sentiment isn't a statistic, but it shapes spending.
What's Confirmed — and What Still Hasn't Been Proven
Confirmed: Brent touched nearly $110 a barrel on Monday, up about 4%, its highest since May, then eased to around $107 on Tuesday. The move raised concerns about inflation and borrowing costs. JPMorgan's research puts 1980 household gasoline spending at roughly 6% of income.
Unproven: whether this price level holds, whether it passes into core inflation, how policymakers will weigh it, and whether the "not the real threat" framing survives a prolonged stretch above $100. Anyone offering a firm answer today is guessing. This report relies on the original source material; no independently verified primary sources were available at the time of writing.
The Case Against Complacency
The reassuring reading of $100 oil has a weakness: it is a calm-market argument. It assumes the spike stays a spike and the supply picture stays boring. A disruption that turns a spike into a plateau would invalidate the entire thesis.
Several risks sit on the other side of the ledger. A supply shock; a weaker dollar making crude costlier for importers; knock-on pressure on food prices through fertiliser and transport; and a tight labour market that quietly converts energy costs into wage demands.
There is also political risk. Pump prices are among the most visible prices in any economy. Voters register them regardless of what a percentage-of-income chart says — and that reaction can shape policy.
A Different Economy, the Same Old Shock Playbook
The broader pattern is a widening gap between what economists measure and what households feel. Markets now price energy shocks faster and more precisely than they did in the 1970s, which shortens the panic. But the political and emotional voltage of fuel prices hasn't fallen at all.
That mismatch — softer economic impact, undiminished public sensitivity — is likely to define how the next several oil cycles are reported.
What This Means for Your Bills, Your Portfolio and Your Plans
For households, the practical advice is unglamorous: don't rebuild a monthly budget around one week's move. Long-distance commuters should expect fuel to be the first line item to shift, and the last to fall back.
For investors, energy exposure cuts both ways, and headline oil moves often reverse within weeks. For borrowers, the signal to track is core inflation, not crude. For small businesses, this is a prompt to review freight contracts and hedging — not to panic.
What Could Change the Story Next
The next inflation prints, central bank commentary, and production and inventory signals will matter more than any single day's barrel price. Watch whether crude holds above $100 for weeks rather than days, whether core inflation moves in response, and whether fuel surcharges start appearing in freight rates. Those are the markers that would turn a headline into a problem.
Our Take
"$100 oil is back" is a good headline and a poor indicator. The story worth following isn't the number on the board — it's how long it stays there and whether it spreads into wages, services and expectations. The economists arguing that triple-digit crude is no longer the threat it once was are making a defensible case, and the 1980 income-share comparison is the strongest part of it.
But "not the real threat" is not the same as "no threat." The genuine danger would be a sustained high price arriving alongside a softening labour market, when households have neither the savings nor the bargaining power to absorb it. That combination isn't here yet. It is, however, the thing to watch.
Frequently Asked Questions
Is oil above $100 bad for the US economy?
It is a headwind, not automatically a crisis. Higher crude raises transport and manufacturing costs and can push inflation up. Whether that becomes a genuine economic problem depends on how long the price stays high and whether it spreads into core inflation.
Why do economists say $100 oil isn't as alarming as it used to be?
Because the burden is smaller relative to incomes. In 1980, Americans spent about 6% of their income on gasoline, according to JPMorgan's analysis. Today's economy also uses far less energy per dollar of output, weakening the link between the barrel price and overall growth.
What oil price level would actually hurt the US economy?
Economists are wary of single thresholds. The damage comes from duration and pass-through rather than the price level itself — a brief spike above $100 is absorbed, while a prolonged stretch at that level alongside rising core inflation and wage pressure is a different problem.
How does oil affect inflation and interest rates in the US?
Oil feeds into fuel, freight and production costs, which can lift headline inflation. Central banks watch core inflation more closely, so a contained energy spike may not shift interest rate decisions. If energy costs start feeding into wages and services, the pressure on borrowing costs becomes far more real.